General information and education, not investment advice. The author is not a SEBI-registered adviser or research analyst. No recommendation, no promised returns. Markets carry risk including loss of capital. Figures may not be current. Always consult a SEBI-registered adviser.
1. At a Glance
Revenue for the June 2026 quarter came in at ₹93.71 crore, up 20.9% against ₹77.53 crore a year earlier. Net profit was ₹8.35 crore versus ₹5.57 crore, a 49.9% move. Operating profit was ₹13.76 crore at an OPM of 14.68%.
That is the arithmetic. The rest of the quarter was a company that spent four decades quietly heating steel until it agreed to become a flange, and has now decided its next act involves 155 mm artillery shells at Butibori, Nagpur, for an estimated ₹250 crore. An advance of ₹28.59 crore had already been paid out by 30 June 2026. For a company whose entire FY26 revenue was ₹338.03 crore, this is not a bolt-on; it is a second company being grown in a field.
Meanwhile the existing business continued doing existing-business things. FY26 capex was ₹15.31 crore. R&D was ₹34.54 lakh, up from ₹21.82 lakh — a number that fits comfortably inside the rounding error of the Nagpur project and yet has produced two granted Indian patents, one of them co-owned with a Japanese university.
Crisil reaffirmed the ratings at BBB/Stable and A3+ on 29 June 2026, while enhancing the rated bank facilities from ₹102 crore to ₹282 crore. Somewhere in that jump sits a ₹180 crore rupee term loan maturing in 2036, which is Union Bank of India agreeing to be part of the story for the next decade.
The segment disclosure in the June quarter now carries a third line item: “Ammunition manufacturing unit,” with segment assets of ₹48.82 crore and nil revenue.
2. Introduction
Incorporated in 1982, Pradeep Metals manufactures and sells forged and machined components. The plant is at Rabale, Navi Mumbai — an industrial estate address that has been on the letterhead long enough to feel like a family surname.
The international expansion happened the sensible way: during 2013-14, the company set up its 100% subsidiary PML Inc. USA to find customers and push exports into America. That subsidiary in turn has a step-down subsidiary, Dimensional Machine Works LLC, which manufactures precision machined components. Crisil combines all three as the PML group, which is the accounting equivalent of a family photo where everyone finally stands still.
The last eighteen months have been busier than the previous eighteen years. In March 2025 the board approved a Scheme of Amalgamation of Nami Capital Private Limited into the company — no cash consideration, just equity issued to NCPL shareholders on an approved exchange ratio, and a stated aim of simplifying the group structure. NCPL happens to hold 59.03% of Pradeep Metals, so “simplifying the group structure” here means removing a layer of holding company that currently sits between the promoters and the shares. BSE conveyed no adverse observation in July 2025. NCLT passed the First Motion Order on 8 April 2026, shareholders met by video conference on 12 June 2026 and approved it, and the Second Motion Petition is now filed. The scheme becomes effective when the NCLT order arrives and is filed with the Registrar of Companies — a sentence that has been true, in various tenses, since March 2025.
The defence project moved on a parallel track and slightly faster. The board approved a ₹250 crore greenfield project on 30 January 2026. On 30 April 2026 the company published a clarification on a Dainik Bhaskar news item, describing it as speculative and pointing back to the January approval — the corporate equivalent of “we already said that, in writing, with a scrip code.” Land at Butibori was identified on 27 April 2026, and a lease assignment deed for 33,040 square metres was executed on 16 June 2026. The 43rd AGM on 7 August 2026 noted the investment, and reappointed Dr. Kewal Krishan Nohria and, for three years, Pradeep Goyal as Chairman & Managing Director.
US
Now live
US Stocks terminal is live
13,000+ US tickers · EDGAR fundamentals · screener and filings feed — the same terminal, for American markets.
Explore →
3. Business Model: WTF Do They Even Do?
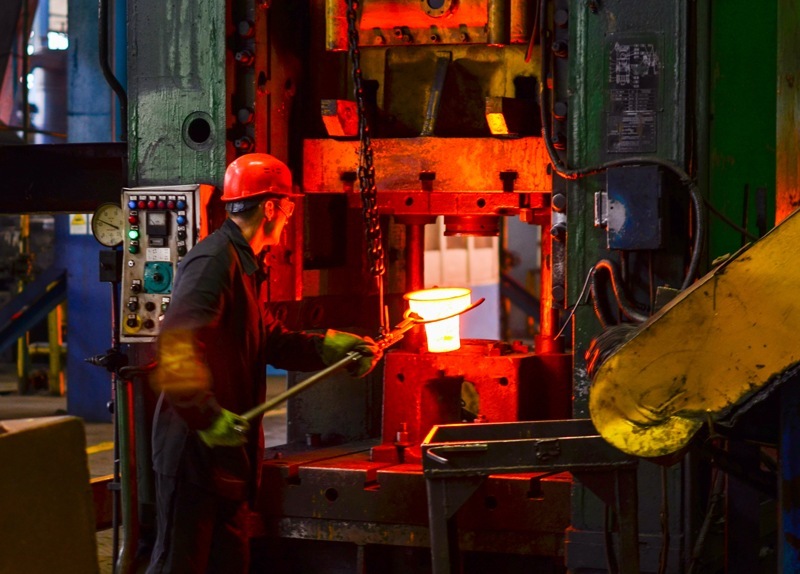
They take steel, get it very hot, and hit it in a closed die until it becomes a specific shape that a Danish valve company urgently needs.
More formally: closed-die stainless steel, alloy steel and carbon steel forgings, supplied as finished and semi-finished machined components to oil and gas, petrochemical and general engineering. The in-house capability list runs from raw material cutting through forging, die tooling, heat treatment, finishing, CNC machining, sub-processing, coating, polishing and surface finishing — which is to say the metal enters as a bar and leaves as a product without ever having to be couriered to a specialist across town.
The hardware behind that: 13,000 MT of installed forging capacity, 80-plus CNC machines, multi-axis machining, in-house die manufacturing, and 4 tonnes of heat treatment capacity. During FY26 the facility ran at 65% capacity utilisation, achieved 88% on-time delivery, developed 300-plus new products and recorded 48% export growth.
Three hundred new products in one year, at a company that manufactures things called NRV cones and wedge shoes. Product-wise, FY26 revenue split as General Engineering & Instrumentation ~34%, Flanges ~33%, Valves ~30%, and Defence ~3%. The defence slice is the one everyone is watching and currently the smallest one on the plate.
The user-industry list reads like a very specific pub quiz: bomb shells and gun parts for defence and aerospace; valve cones and valve