Section 1 — At a Glance
Maithan Alloys Limited closed its fiscal year 2026 presenting a stark divergence between operational reality and headline profitability. Total revenue from operations stood at ₹2,172.59 crore, marking a 20.6% recovery over the previous fiscal year. However, the core business continues to experience profound structural pressure, with operating profit margins suppressed at 11.9% relative to historical peaks that routinely exceeded 20% to 30%. While the reported annual net profit reached ₹433.65 crore, a deeper audit reveals that the bottom line was heavily insulated by an extraordinary other income component of ₹411.96 crore.
Investor attention is increasingly drawn to the company’s aggressive balance sheet transformation, where total investments have ballooned to ₹2,840.36 crore. Conversely, severe concerns are mounting over the core manufacturing operations. The company’s fourth quarter ended March 31, 2026, slipped into a sharp net loss of ₹70.44 crore due to a severe hit from other income which turned negative at ₹-158.96 crore, combined with elevated production and power costs.
High non-operating income frequently masks deterioration in a company’s core economic engine, creating a temporary valuation buffer that operational cash flows cannot sustain.
The primary narrative moving forward hinges on whether the group can successfully revive its manufacturing margins or if it will transition structurally into a corporate treasury vehicle masquerading as a manufacturing enterprise.
Section 2 — Introduction
Maithan Alloys Limited operates as one of India’s prominent metallurgical players, specializing in bulk ferroalloys. Over the past two years, the company’s operational narrative has shifted from structural growth to survival and tactical retreat. Rising power tariffs across key manufacturing zones have fundamentally altered the economics of production, forcing strategic closures and asset liquidations. This article evaluates the financial year 2026 results to unpack why a company with massive cash reserves and liquid investments is struggling to generate profitable growth from its core manufacturing lines.
US
Now live
US Stocks terminal is live
13,000+ US tickers · EDGAR fundamentals · screener and filings feed — the same terminal, for American markets.
Explore →
Section 3 — Business Model: WTF Do They Even Do?
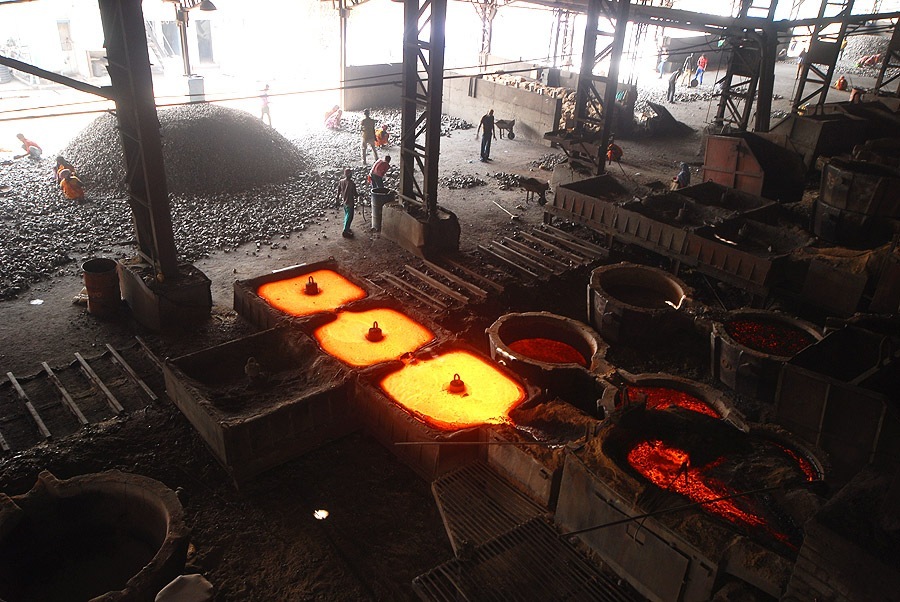
Maithan Alloys transforms imported manganese ore, coke, and coal into the vital ingredients that keep steel from crumbling. It produces three primary bulk ferroalloys: Ferro Manganese, Silico Manganese, and Ferro Silicon. Roughly 1.5% of each tonne of steel produced globally consists of manganese alloy, making Maithan inherently levered