Master Components Ltd H2 FY26: Explosive 75% Top-Line Growth Sparks Capital Expansion Drama
Spotted a factual error — a wrong number, date, or fact? Tell us and we will check the source.
1. At a Glance
A high-velocity micro-cap company reporting a massive surge in annual revenue from ₹42.37 crore to ₹74.38 crore in just twelve months is bound to turn heads. Master Components Ltd (MCL) is experiencing exactly that type of market attention, with its top-line expanding by an eye-popping 75.55% during the 2026 financial year. Net profit jumped in tandem from ₹6.49 crore to ₹7.44 crore. Yet, beneath this shiny veneer of accelerating sales lies a complex financial structure loaded with structural shifts, exploding capital expenses, and a severe crunch in free cash flow that demands an objective investigation.
While investors celebrate the surface-level operational growth, a forensic look at the numbers exposes rising operational friction. For starters, the company’s borrowings have violently ballooned from ₹4.01 crore in FY25 to a massive ₹10.86 crore in FY26. This leverage injection was deployed directly into long-term blocks and aggressive land purchases, triggering a spike in yearly interest expenses from ₹0.19 crore to ₹0.82 crore. Simultaneously, the working capital architecture is being pushed to its limits. Receivables expanded heavily from ₹9.21 crore to ₹14.88 crore, meaning a large chunk of that highly celebrated revenue growth is still sitting as unpaid invoices on the books of corporate clients rather than real cash in the bank.
The most critical stress signal emerges from the cash flow statement. Despite booking a record high operating profit of ₹12.30 crore, the enterprise is losing cash on a net basis across its core investment cycle. Its structural free cash flow has remained deep in negative territory for three consecutive years, bleeding ₹9.77 crore in FY24, ₹3.08 crore in FY25, and continuing its cash-guzzling streak into FY26 due to aggressive capital deployment. With an impending corporate amalgamation of its subsidiary Master Moulds on the horizon, the stakes are exceptionally high. Will this massive operational scaling lead to real wealth creation, or is the business running on an expensive, leverage-fueled treadmill?
2. Introduction
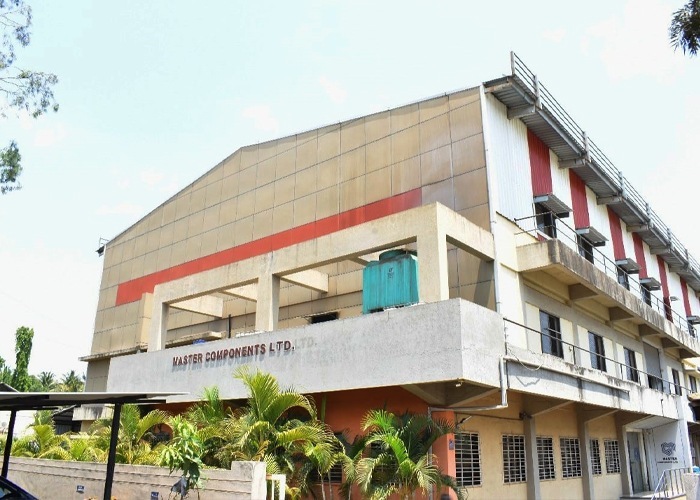
Master Components Ltd operates deep within the specialized niche of industrial engineering, acting as a key manufacturing partner for heavy electrical, automotive, and medical enterprises. For a micro-cap company with a total market capitalization of ₹136 crore, navigating B2B client relationships with multi-billion-dollar global conglomerates requires high technical precision and strict quality compliance. The stock currently commands a price of ₹340 on the NSE SME platform, trading at a Price-to-Earnings (P/E) ratio of 18.28, which sits comfortably below the broader plastic industrial products median P/E of 20.70.
A clear understanding of corporate accounting requires distinguishing standalone statements from consolidated realities. When an expanding enterprise runs multiple sub-units or enters joint ventures, analyzing standalone parent figures can obscure massive capital drains or hidden debt piles operating inside subsidiaries. This analysis relies entirely on the complete financial performance of Master Components Ltd, assessing whether its internal cash generation is sufficient to sustain its aggressive corporate ambitions.
Over the past five years, the company has established a compounded sales growth rate of 41% and a compounded profit growth rate of 58%. This long-term trajectory indicates that the recent performance isn’t a temporary spike, but part of a sustained commercial expansion. However, scaling an industrial manufacturing outfit requires continuous investments in land, heavy machinery, and inventory, turning the company into a capital-intensive operation that requires constant monitoring.
At its core, Master Components Ltd is a high-precision plastic cook. They do not manufacture ordinary consumer plastic goods; instead, they specialize in high-performance Plastic Engineering Components and complex sub-assemblies designed to survive extreme industrial environments. The company holds specialized IATF 16949:2016 and ISO 9001:2015 certifications, which serve as mandatory entry tickets to supply critical components to global engineering giants.
Their industrial processes include:
Thermoplastic Injection Moulding: Melting polymers and injecting them under intense pressure into highly custom steel moulds.
Thermoset Injection & Compression Moulding: A highly precise chemical process where plastics cross-link permanently, meaning they will never melt again, making them perfect for high-voltage circuit breakers.
Transfer Moulding: Used for intricate, heavy-duty industrial components requiring tight dimensional tolerances.
The company’s end-market profile spans electrical switches, automotive body parts, medical devices, and heavy industrial machinery. Their client list includes global powerhouses like Siemens, Schneider Electric, Legrand, L&T Electrical, and Lear Corporation. While having blue-chip clients validates their technical capability, it creates a tough working relationship: these massive clients command immense bargaining power, often enforcing long payment cycles that lock up MCL’s cash in receivables for extended periods.
4. Financials Overview
Because Master Components Ltd reports its interim financial numbers under the Half-Yearly framework rather than standard quarters, we track its performance in consecutive six-month blocks. To calculate the annualized valuation correctly, the latest half-yearly EPS (H2 FY26) of ₹10.50 is annualized by multiplying by two, yielding an annualized EPS baseline of ₹21.00.
Half-Yearly Financial Performance Comparison
Metric
Latest Half Year (H2 FY26)
Same Period Last Year (H2 FY25)
Previous Half Year (H1 FY26)
YoY Change (%)
QoQ/HoH Change (%)
Revenue
₹37.61 cr
₹24.67 cr
₹36.77 cr
+52.45%
+2.28%
EBITDA
₹6.97 cr
₹3.54 cr
₹5.32 cr
+96.89%
+31.02%
PAT
₹4.20 cr
₹4.82 cr
₹3.24 cr
-12.86%
+29.63%
EPS (₹)
₹10.50
₹12.05
₹8.10
-12.86%
+29.63%
Source: Official Company Half-Yearly Financial Filings
The operational performance reveals a sharp contrast. On a year-over-year basis, H2 FY26 revenues grew an impressive 52.45% to ₹37.61 crore. EBITDA almost doubled, climbing from ₹3.54 crore to ₹6.97 crore, driven by strong operating profit margins which recovered back to 18.53%. However, despite this strong operational performance, half-yearly Net Profit actually fell by 12.86% YoY to ₹4.20 crore.
Why did PAT drop while operational profits boomed? The answer lies in the company’s aggressive expansion strategy. Interest charges jumped from ₹0.16 crore to ₹0.55 crore, and depreciation increased to ₹0.94 crore as new assets came online. This highlights a valuable financial lesson: aggressive, debt-funded capital expenditure can depress net earnings even while the core factories are running at full capacity.
:list –>
The Debt Comeback: After achieving a virtually debt-free balance sheet in FY24 (-₹0.14 crore), the company took on significant leverage, with total debt climbing to ₹10.86 crore in FY26 to fund its expansion.
The Asset Accumulation: Net fixed block jumped from ₹10.16 crore to ₹27.73 crore as capital expenditure was deployed into heavy manufacturing machinery.
The Working Capital Strain: Other assets—which include raw inventories and unpaid trade receivables—nearly doubled from ₹15.54 crore to ₹31.14 crore, tying up substantial liquidity.
8. Cash Flow – Sab Number Game Hai
Looking at the cash flow statement helps cut through accounting adjustments to see the actual movement of cash in the business.