General information and education, not investment advice. The author is not a SEBI-registered adviser or research analyst. No recommendation, no promised returns. Markets carry risk including loss of capital. Figures may not be current. Always consult a SEBI-registered adviser.
1. At a Glance
Cupid Limited closed the June 2026 quarter with revenue of ₹156.99 crore and net profit of ₹44.16 crore. Against ₹64.74 crore and ₹15.02 crore in the same quarter a year earlier, that is sales growth of 142% and profit growth of 194%. Operating profit came in at ₹62.33 crore, on an OPM of 40%.
Sequentially, the March 2026 quarter’s ₹132.04 crore and ₹36.26 crore became ₹156.99 crore and ₹44.16 crore — a company that has now spent six straight quarters making its own previous quarter look like a warm-up act.
Around the numbers, the corporate calendar has been doing overtime. The board met on 7 August 2026 for 48 minutes — commencement 4:15 PM, conclusion 5:03 PM, a runtime somewhere between a sitcom and a school assembly — and in that time noted the results, re-appointed the cost auditors, approved the Directors Report, approved the AGM notice, and granted in-principle approval to explore a project in West Bengal. On 17 August the company appointed Shri Keral Prasad Yadaw as additional independent director for five years. On 17 and 18 August, promoter Aditya Kumar Halwasiya bought shares in the open market, taking promoter holding to 46.40%.
FY26 as a whole closed at ₹391.40 crore of income and ₹108.26 crore of net profit, with EPS of ₹0.81. The share count is the reason that EPS number looks the size it does — 4:1 bonus shares were allotted in March 2026, and the paid-up capital went from ₹26.85 crore to ₹134.47 crore. More on the arithmetic of that below.
2. Introduction
Cupid was established in 1993 and describes itself as India’s premier manufacturer of male and female condoms, personal lubricant and IVD kits. It is, per the company, the first in the world to receive WHO/UNFPA prequalification for both male and female condoms — a sentence that sounds modest until you notice how few companies on earth are in a position to say it.
For most of its listed life the company was a modest exporter with a factory in Sinnar, Nashik, sitting on roughly 100,000 sq ft and turning out somewhere between ₹80 crore and ₹160 crore of sales a year. Sales were ₹83.64 crore in FY17 and ₹159.22 crore in FY23 — six years in which the company grew, but at the pace of a business that ships to health ministries rather than one that chases quarterly narratives.
The ownership changed in October 2023, when Columbia Petro Chem Private Limited and Mr. Aditya Kumar Halwasiya acquired a 41.84% stake for ₹159.06 crore. Mr. Kuldeep Halwasiya was appointed Chairman, Mr. Aditya Halwasiya Managing Director, and in January 2024 Mr. Ajay Halwasiya joined as executive director.
What followed reads like a company that found the accelerator pedal it had been using as a footrest. FY26 sales of ₹391.40 crore against FY25’s ₹183.01 crore. Board approval in December 2025 for an FMCG manufacturing facility in Saudi Arabia. A December 2024 land acquisition near Mumbai to take male condom capacity to 1.25 billion units and female to 125 million. A November 2025 allocation under South Africa’s 2025–2030 national procurement programme — 23.4 million female condoms annually at a 59% share, plus 0.77 million boxes of male condoms, which the company puts at roughly ₹115 crore of annual revenue visibility. Authorised capital raised from ₹50 crore to ₹150 crore in January 2026. A 4:1 bonus in March. A ₹331.53 crore strategic investment in Baazar Style Retail Limited, of which ₹82.88 crore was paid in April 2026 for 1.01 crore convertible warrants.
Also pending, per the company’s disclosures: a civil case, Vikas Lifecare Ltd Vs M/s Cupid Ltd & Ors, in the District Court at Alwar, Rajasthan, concerning the sale and purchase of shareholdings in Cupid.
US
Now live
US Stocks terminal is live
13,000+ US tickers · EDGAR fundamentals · screener and filings feed — the same terminal, for American markets.
Explore →
3. Business Model: WTF Do They Even Do?
Cupid makes contraceptives, and then — having built a factory that dips latex for a living — decided that as long as the dipping lines were running, it may as well also sell you a talcum powder.
The core is condoms. FY26 revenue contribution, per the company: male condoms ₹181.11 crore (51.60%), female condoms ₹60.72 crore (17.27%), IVD kits and lubricants ₹24.97 crore (7.11%), and new FMCG products ₹84.26 crore (24.01%). Installed capacity stands at 480 million male condoms and 52 million female condoms a year, plus 210 million lubricant sachets and 20 million IVD test kits. Sale volume of male condoms was 378.86 million pieces in the most recent disclosed year.
The buyers are the interesting part. This is substantially a B2B tender business — exports contributed ₹208.13 crore, or 59.30% of FY26 revenue, across 125+ countries, sold to WHO/UNFPA, PFSCM, Global Fund, MSI, PSI and the IDA Foundation. Somewhere in a procurement office in Geneva, a spreadsheet decides Cupid’s quarter. It is possibly the only consumer-adjacent product category where the largest customers are multilateral institutions and the smallest is a chemist in Nashik.
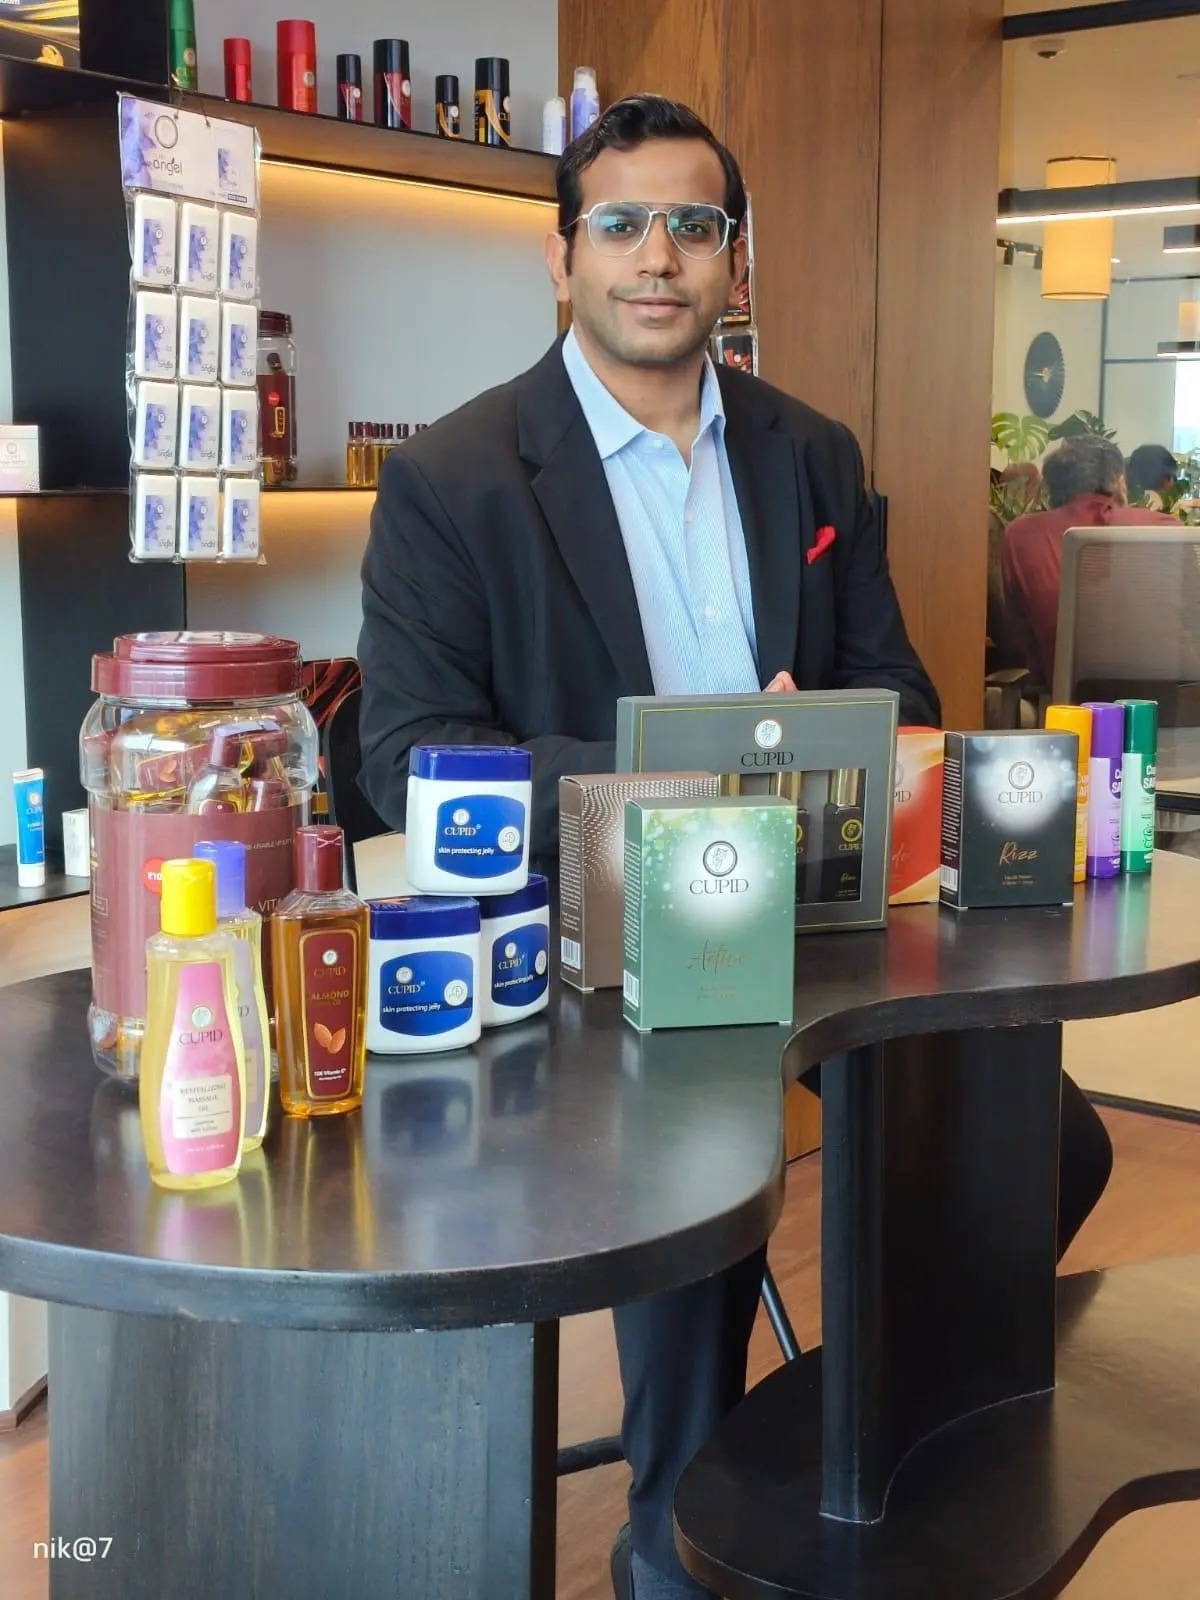
Then there is the other half of the identity crisis, and it is a productive one. The FMCG list runs: deodorants, perfumes, almond hair oil, body oils, petroleum jelly, face wash, sunscreen, shower gel, body mist, hand wash, colour cosmetics and talcum powder in 20gm and 100gm. New launches in FY26 included flavoured condoms in banana and grape, super dotted with benzocaine, Cupid Angel fragrances in Bling, Passion and Bloom, and a face wash sold 24 pieces to a jar. The product architecture has quietly become a full bathroom shelf that happens to have started at one very specific corner of it.
Distribution has scaled to match: 1,050 distributors and 1.50 lakh+ retail outlets, broken down as 75,043 chemists, 47,543 cosmetics outlets, 12,584 groceries, 12,346 pan-plus and 2,983 open format, with 2,934+ modern trade stores listed and