General information and education, not investment advice. The author is not a SEBI-registered adviser or research analyst. No recommendation, no promised returns. Markets carry risk including loss of capital. Figures may not be current. Always consult a SEBI-registered adviser.
1 — At a Glance
Revenue from operations for the June 2026 quarter came in at ₹1,545 Cr, up 20.2% from ₹1,286 Cr a year ago. Operating profit was ₹247 Cr against ₹229 Cr, up 7.9%. Net profit was ₹165 Cr against ₹168 Cr, down 1.7%. Three numbers, three different directions, all in the same three months.
Management’s explanation for the PAT line is on record and specific: growth would have been similar to EBITDA growth excluding a one-time benefit in the year-ago quarter from selling the Motocare business and other one-off income. The CFO also pointed at commodity escalation tied to the geopolitical situation and the cost of moving from a private to a listed company — the company completed its IPO in November 2025, so this is the first Q1 where being publicly listed shows up as a line item rather than an aspiration.
Elsewhere on the scoreboard: value-added revenue grew 18.4% to ₹13,816 million against served-market volume growth of 16.2%. Commercial vehicle Clean Air value market share moved to 58% in FY26. Passenger vehicle shocks and struts went to 55%. Off-highway Clean Air held at 68%. A spark plug order landed from what management called one of India’s largest passenger vehicle OEMs, described as entry into a new whitespace.
Operating margin was 16% of revenue in the June quarter, against 18% a year earlier. The market currently pays 35.0x earnings against an industry P/E of 29.7. And on August 12, the promoters sold 6.05 crore shares.
Which is a lot of things happening at a company that mostly makes exhaust pipes and shock absorbers.
2 — Introduction
Tenneco Clean Air India Limited was incorporated in 2018 and is a subsidiary of Tenneco Inc., the U.S. group that designs and manufactures clean air and powertrain products for automotive applications. The parent is a global Tier-1 supplier to major automotive OEMs and to the aftermarket, which means the Indian entity arrived with a customer list rather than having to build one.
The equity shares listed on BSE and NSE on 19 November 2025, following an IPO of 9,06,80,100 equity shares of ₹10 face value at an issue price of ₹397 per share — entirely an offer for sale by selling shareholders, raising ₹3,600 crore that went to those shareholders rather than into the company. The float was 61.8x subscribed.
The recent filing record runs at a steady clip. In February 2026, the board approved a Kharkhoda factory with ₹710 million of capex, adding roughly 130,000 cold-end and 256,000 hot-end units. In May 2026, a subsidiary approved a new Western India factory adding 2.1 million units with ₹690 million of investment by FY28. The Q3 FY26 transcript disclosed program wins of ₹2,200 million and ₹1,150 million. The FY26 results release in May 2026 reported an 18.8% EBITDA margin for the year.
Statutory auditors are Deloitte Haskins & Sells LLP. The June 2026 consolidated results were subjected to limited review, and the review report states nothing came to the auditor’s attention causing them to believe the statement contained material misstatement. The standalone results carried an unmodified conclusion.
The consolidated group includes four subsidiaries: Tenneco Automotive India Private Limited, Federal-Mogul Ignition Products India Limited, Federal-Mogul Sealings India Limited, and Federal-Mogul Bearings India Limited. For accounting purposes, the group treats itself as a single segment under Ind AS 108 — manufacturing of automotive equipment, parts and components — so there are no separate reportable segments in the financials, even though the business talks about itself in two halves.
US
Now live
US Stocks terminal is live
13,000+ US tickers · EDGAR fundamentals · screener and filings feed — the same terminal, for American markets.
Explore →
3 — Business Model: WTF Do They Even Do?
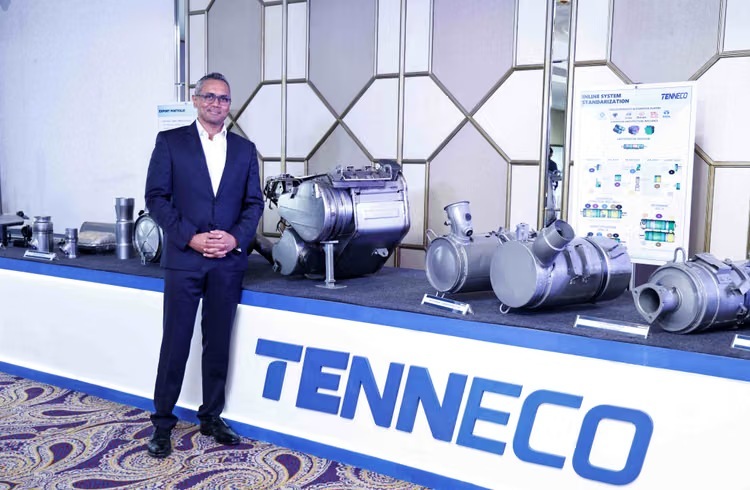
Two halves, then. Clean Air & Powertrain Solutions makes the things that sit between an engine and the atmosphere and try to make the second one less angry about the first: exhaust after-treatment systems, catalytic converters (DOC, DPF, SDPF, SCR — the alphabet of not choking), mufflers, exhaust pipes. Bolted onto the same division are engine bearings including IROX technology, sealing systems covering cold and hot gaskets and heat shields, and ignition products — spark plugs and coils under the Champion brand.
Advanced Ride Technologies is the other half: passive and semi-active shock absorbers and struts, electronic and semi-active dampers, advanced suspension modules. This is the business of converting Indian road surfaces into a rumour the passenger merely hears about.
The split by value-added revenue was 52.5% Clean Air & Powertrain and 47.5% Advanced Ride. By end market: passenger vehicles 63.5%, commercial vehicles 21.5%, industrial and others 7%, aftermarket 5.5%, others 2.5%. Domestic sales were 93% of VAR in FY25, exports 6.5%, going to 18–22 countries across the Americas, Europe, APAC and Africa — the U.S., Germany, the U.K., Brazil, Mexico, Japan, Thailand, Vietnam.
Twelve manufacturing facilities across seven states and one union territory: seven Clean Air & Powertrain plants and five Advanced Ride plants, in Maharashtra, Tamil Nadu, the NCR and Gujarat. Two dedicated R&D technical centres support localisation and product development.
The customer roster ran to 119 in FY25, including all top seven PV OEMs and all top five CT OEMs in India — Maruti Suzuki, Tata Motors, Mahindra & Mahindra, Hyundai and Ashok Leyland among the named ones. The top ten customers account for 80% of