General information and education, not investment advice. The author is not a SEBI-registered adviser or research analyst. No recommendation, no promised returns. Markets carry risk including loss of capital. Figures may not be current. Always consult a SEBI-registered adviser.
1. At a Glance
Revenue of ₹1,624 crore for the June 2026 quarter, up 25.5% from ₹1,293 crore. Operating Profit of ₹167 crore against ₹170 crore a year ago — the revenue line sprinted, the profit line stayed exactly where it was and pretended nothing happened. PAT of ₹89 crore, up 11%. EPS ₹25.23 against ₹16.61.
The order backlog including MDO stands at ₹55,398 crore. Annual revenue for FY26 was ₹6,062 crore. That backlog is roughly nine times what the company sells in a year, which in most industries would be called a planning horizon and in engineering and construction is called Tuesday.
Q1 order inflow was ₹1,864 crore, which management describes as 15.5% of an FY27 target of ₹12,000 crore. Among the wins: a five-year O&M contract for the Mumbai Monorail, a system that has spent most of its existence being India’s most discussed two-carriage transport debate, and which now has a boiler-erection specialist looking after it.
Management attributes the lower margin to higher royalty costs in the KRBM project following a Government Order on royalty sharing for seized quantities, higher overburden removal costs at the KBP mine, and increased material costs from the ongoing Middle East conflict. Three separate explanations, three separate continents’ worth of causes, one 320-basis-point EBITDA margin move.
CARE Ratings reaffirmed CARE A+; Stable / CARE A1 on August 17, 2026, with the rated facility enhanced to ₹2,900 crore. FY26 closed with revenue of ₹6,062 crore and PAT of ₹412 crore.
2. Introduction
Power Mech Projects Limited was incorporated in 1999 and is a Hyderabad-based company promoted by Sajja Kishore Babu, Chairman and Managing Director. It began, per the company’s own timeline, with gas turbine overhauling for a major utility — which is roughly the industrial equivalent of starting a restaurant empire by fixing someone else’s oven.
Between 2000 and 2010 it built out erection, testing and commissioning of boilers and turbines, plus overhauling and maintenance contracts for large power plants. From 2010 to 2015 it diversified into non-power sectors — industrial plants, rail and metro, water — and entered overseas markets. It prepared for public listing around 2014-15. From 2016 to 2020 the company describes a phase of consolidation and service leadership. From 2020 to 2026, entry into mining and a large order-book scale-up. The stated ambition for 2027 and beyond is to become a global integrated services provider, a phrase that appears in roughly one in three Indian annual reports and has never once been accompanied by a diagram anyone understood.
CARE notes an operational track record of over 27 years in ETC of boiler, turbine and generator, balance of plant, civil works and O&M of power plants. The company executed ETC-BTG works for the first two ultra-mega power projects — Mundra and Sasan — and 19 other supercritical power projects across India.
The last twelve months have been busy in the way construction companies are busy: in ₹1,000-crore increments. A ₹1,008.90 crore civil and structural order from JSW Thermal Energy for Salboni in June 2026. A ₹709.56 crore O&M and overhauling contract for the 5x660MW Tiroda plant in March. Over ₹2,500 crore of EPC BoP work from BHEL for the 1x800MW Singareni TPS in October 2025. Also in March 2026, WBSEDCL annulled the tender and cancelled the letter of award issued to subsidiary PM Green for a 250MW/1000MWh battery storage project, removing ₹1,563 crore from the order book, with guarantees released.
Consolidation covers 35 entities per CARE’s annexure, spanning Oman, Nigeria, Dubai, Saudi Arabia and Qatar, plus fourteen-odd domestic joint ventures with names that read like a hostage list of acronyms. Somebody at Power Mech maintains that spreadsheet, and they deserve better.
US
Now live
US Stocks terminal is live
13,000+ US tickers · EDGAR fundamentals · screener and filings feed — the same terminal, for American markets.
Explore →
3. Business Model: WTF Do They Even Do?
Five segments, and the honest summary is: they build the power plant, then they stay and run it, and lately they also dig up the coal that goes into it.
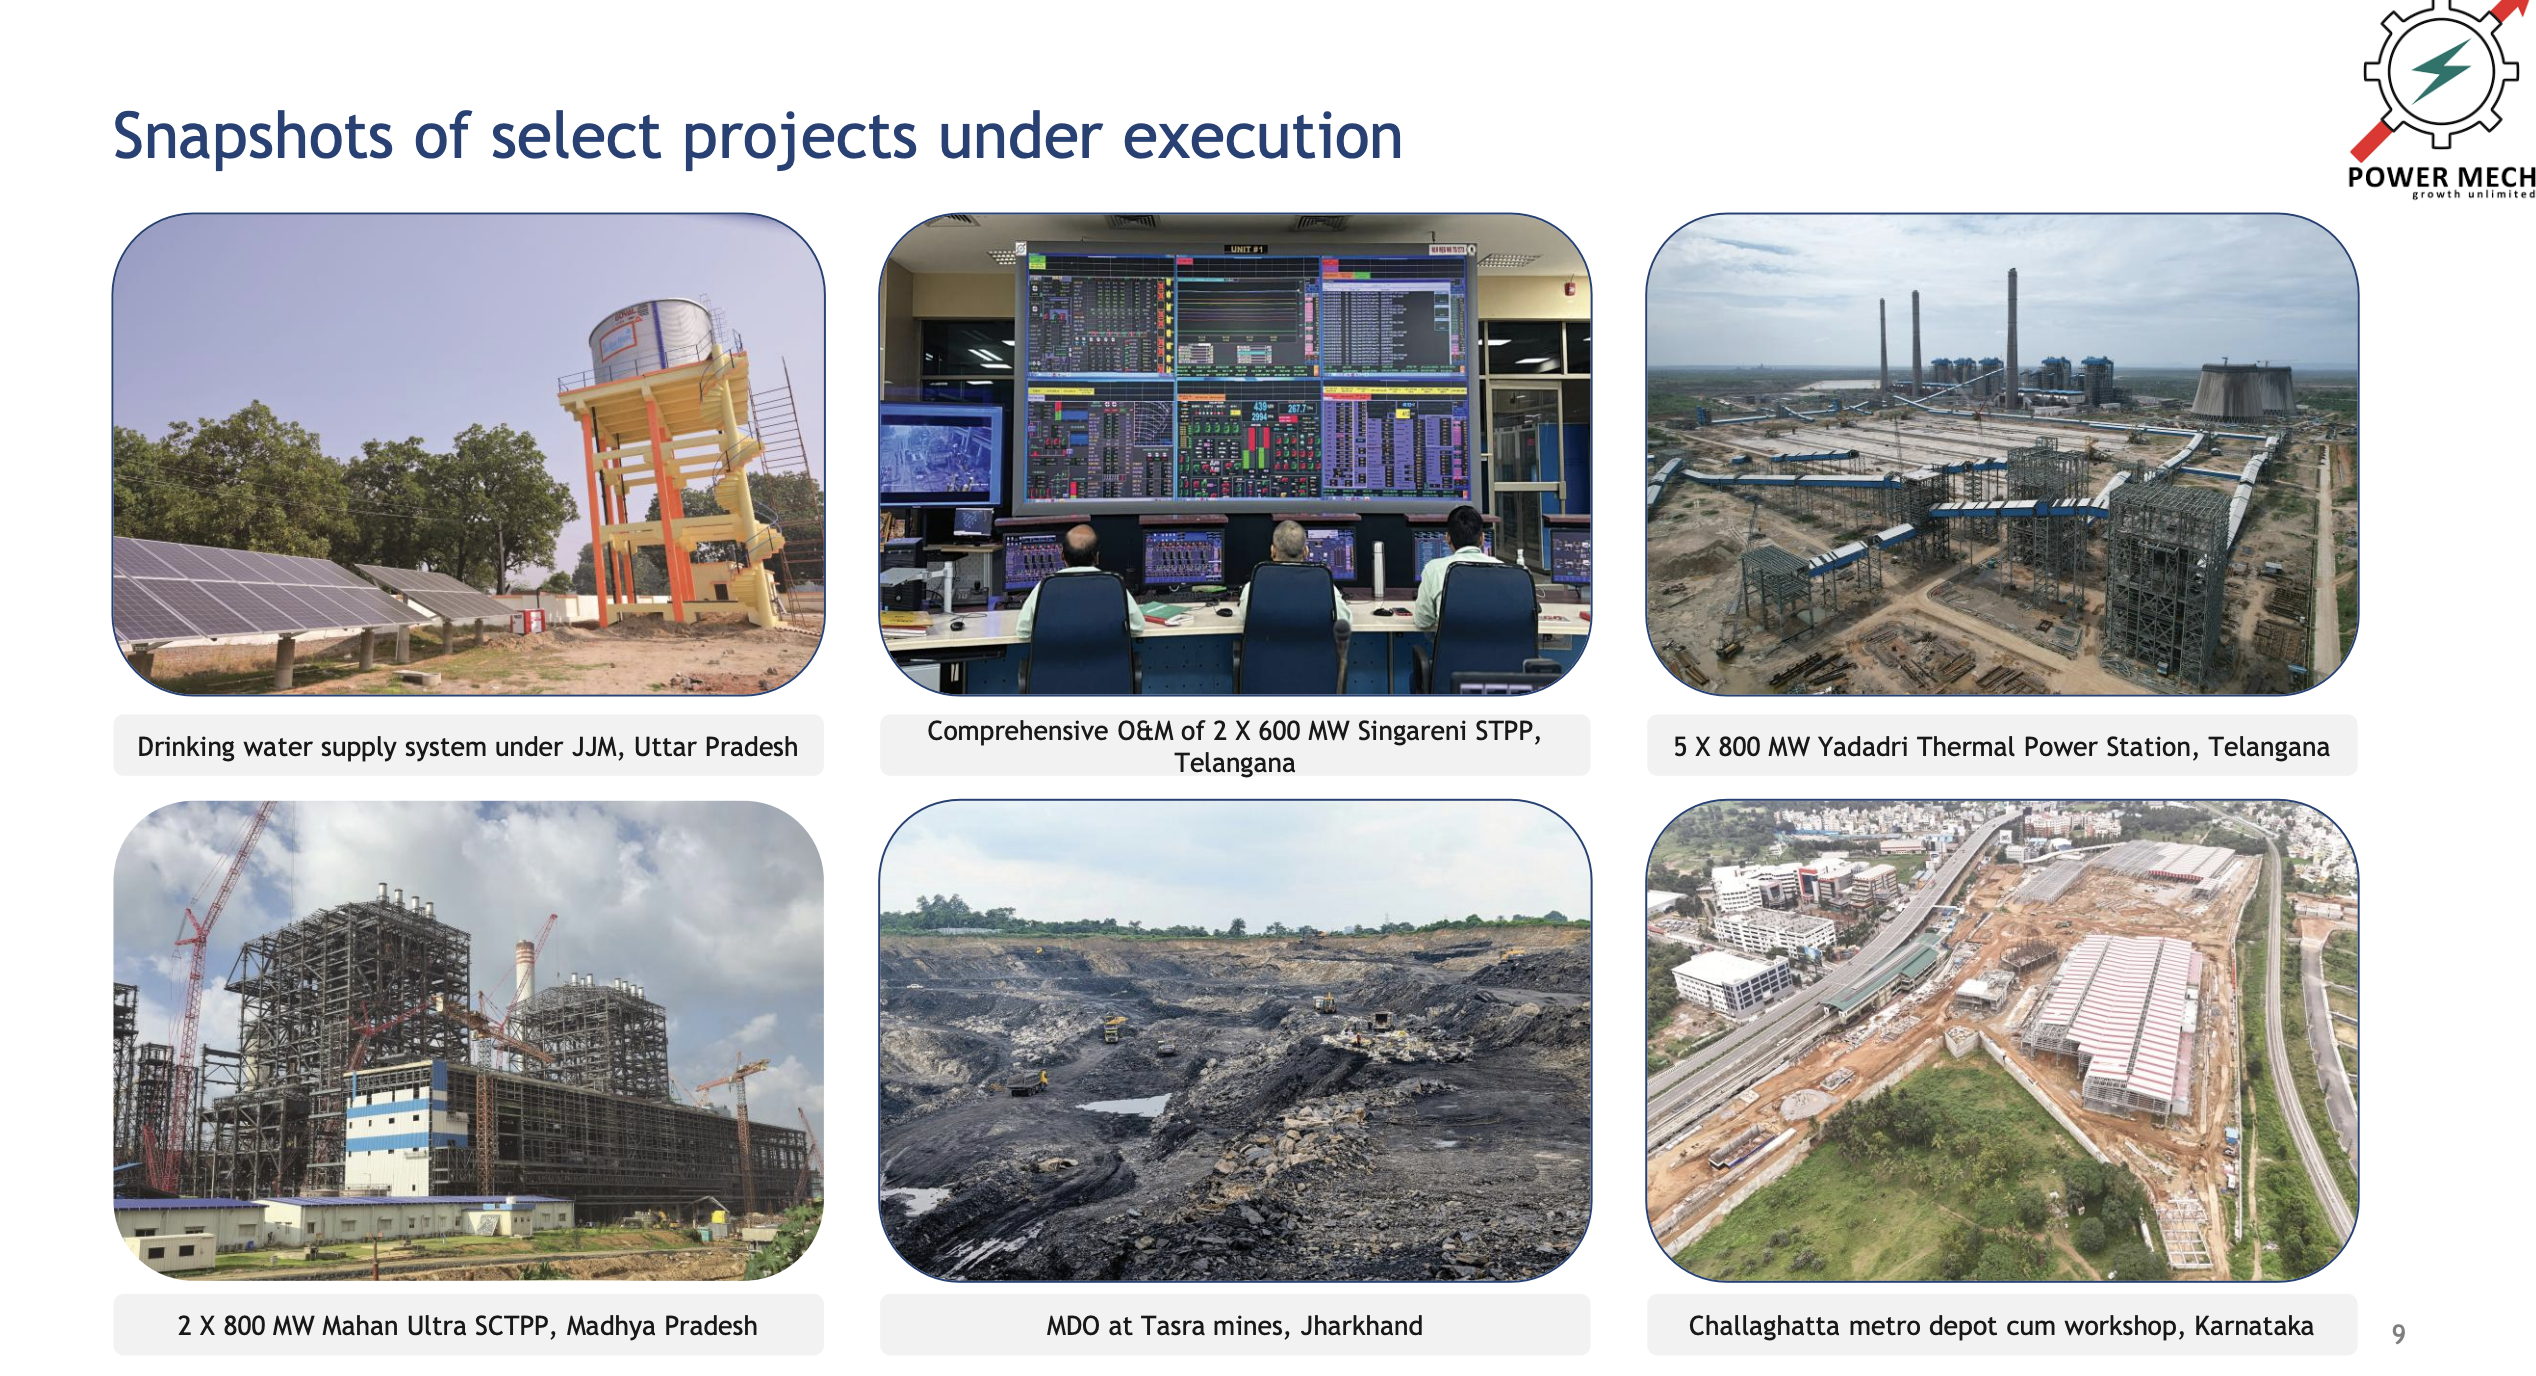
Erection, Testing & Commissioning is full-scope assembly of BTG/BOP systems including FGD and SCR, across power, nuclear, oil & gas, petrochemicals, steel and minerals. Cumulative erection works: 31.22 lakh MT. This is the founding business, and management describes its physical ceiling with unusual candour — the company can execute 14 to 15 boilers of 800 MW simultaneously, and capacity increases by one or two boilers a year. There are companies whose growth constraint is demand, and there are companies whose growth constraint is how many enormous boilers can be under construction at once.
Operations & Maintenance covers 36.25 GW of unit capacity under management: mechanical, electrical and C&I services, control room operations, boiler and turbine overhauls, long-term AMCs. Management describes this as India’s largest power O&M platform with roughly 16% market share. Q1 O&M revenue: ₹431 crore, up 8%.
Civil Infrastructure is foundations, decks, cooling towers, coal handling plants, roads and bridges — 33.47 lakh cubic metres of concreting works cumulatively, a figure that means nothing to a human until you realise it is enough concrete to make every civil engineer at the company sleep very soundly. Q1 civil revenue was ₹796 crore, up 28% and the largest single segment.
Industrial Construction did ₹270 crore, down 30%, with Industrial EPC at ₹96 crore alongside it as management describes a shift toward EPC and BOP packages.
Mining, Development & Operations is the newest room in the house: mine infrastructure development, mineral processing and end-to-end contract mining, with two coal contracts — the 5 MTPA Kotre Basantpur block in Jharkhand and a 4 MTPA coking coal project from SAIL, combined peak capacity 9 MTPA.