General information and education, not investment advice. The author is not a SEBI-registered adviser or research analyst. No recommendation, no promised returns. Markets carry risk including loss of capital. Figures may not be current. Always consult a SEBI-registered adviser.
1. At a Glance
K.P. Energy builds the unglamorous parts of a wind farm. Roads, foundations, substations, and the cables that carry electricity to people who will never think about them.
Revenue from operations for the three months to June 2026 was ₹519.46 crore. The same quarter a year earlier brought ₹219.54 crore, an increase of 137 per cent. Operating profit was ₹60.42 crore, against ₹48.44 crore. Profit after tax was ₹26.08 crore, against ₹25.42 crore. The top line more than doubled and the bottom line moved by roughly the price of a mid-range hatchback. The operating profit margin was 12 per cent, against 22 per cent in the June 2025 quarter.
Management describes the quarter as one that “tested our ability to manage an exceptionally challenging cost and operating environment”. That is the corporate way of saying costs rose everywhere at once.
The order book stood at 2.16 GW as on 30 June 2026, valued at about ₹2,250 crore. Operational capacity as an independent power producer is 48.5 MW. An independent power producer sells electricity to the grid instead of building projects for clients. A further 202 MW of such projects sits in the pipeline.
In July 2026 a 50.4 MW wind project was commissioned for NTPC Renewable Energy. On 1 August a 100 MW power purchase agreement was signed with GUVNL at ₹3.435 per unit. A power purchase agreement fixes the price a buyer pays for electricity over many years. Supply under it begins on 30 July 2028.
2. Introduction
K.P. Energy Limited was incorporated in 2010. It sits inside the KP Group of Surat, founded in 1994 by Faruk Patel. The group runs to more than 50 companies. Their work covers solar, wind, hybrid projects and green hydrogen. Ammonia, battery storage and offshore projects sit alongside those. The list covers most of the acronyms the energy transition has produced since 2010.
K.P. Energy itself does one thing with unusual specificity. It develops utility-scale wind power infrastructure, principally in Gujarat. That means siting the farm, acquiring the land, chasing the permits and building the balance of plant. It also owns wind turbine generators and a solar plant as an independent power producer. That is the part of the business where it bills the grid rather than a client.
The scale-up has been quick. Sales in the year to March 2022 were ₹250 crore. The next year brought ₹438 crore, then ₹471 crore. The year to March 2025 brought ₹936 crore. The year to March 2026 brought ₹1,497 crore. Compounded sales growth over five years is 84 per cent. Compounded profit growth over the same span is 97 per cent.
Equity share capital went from ₹11.12 crore in the year to March 2023 to ₹33.35 crore the year after. The face value moved from ₹10 to ₹5. Face value is the nominal amount printed on a share. That change quietly rearranges every per-share number in the file.
Recent months have been eventful in a paperwork-heavy way. In April 2026 the company received an inter-state electricity trading licence from CERC, the central power regulator. In May, KP Group installed India’s first ‘Make in India’ 4.2 MW M160 turbine in south Gujarat. In July, Prof. Sunil Kumar Maheshwari was appointed Vice-Chairman for five years. Amit Khandelwal resigned with effect from 3 July 2026. In August, MSKC & Associates LLP, a member firm of BDO International, was appointed statutory auditor for five years, subject to member approval. MAAK & Associates complete their tenure at the 17th annual general meeting. Market capitalisation stands at ₹1,715 crore.
US
Now live
US Stocks terminal is live
13,000+ US tickers · EDGAR fundamentals · screener and filings feed — the same terminal, for American markets.
Explore →
3. Business Model: WTF Do They Even Do?
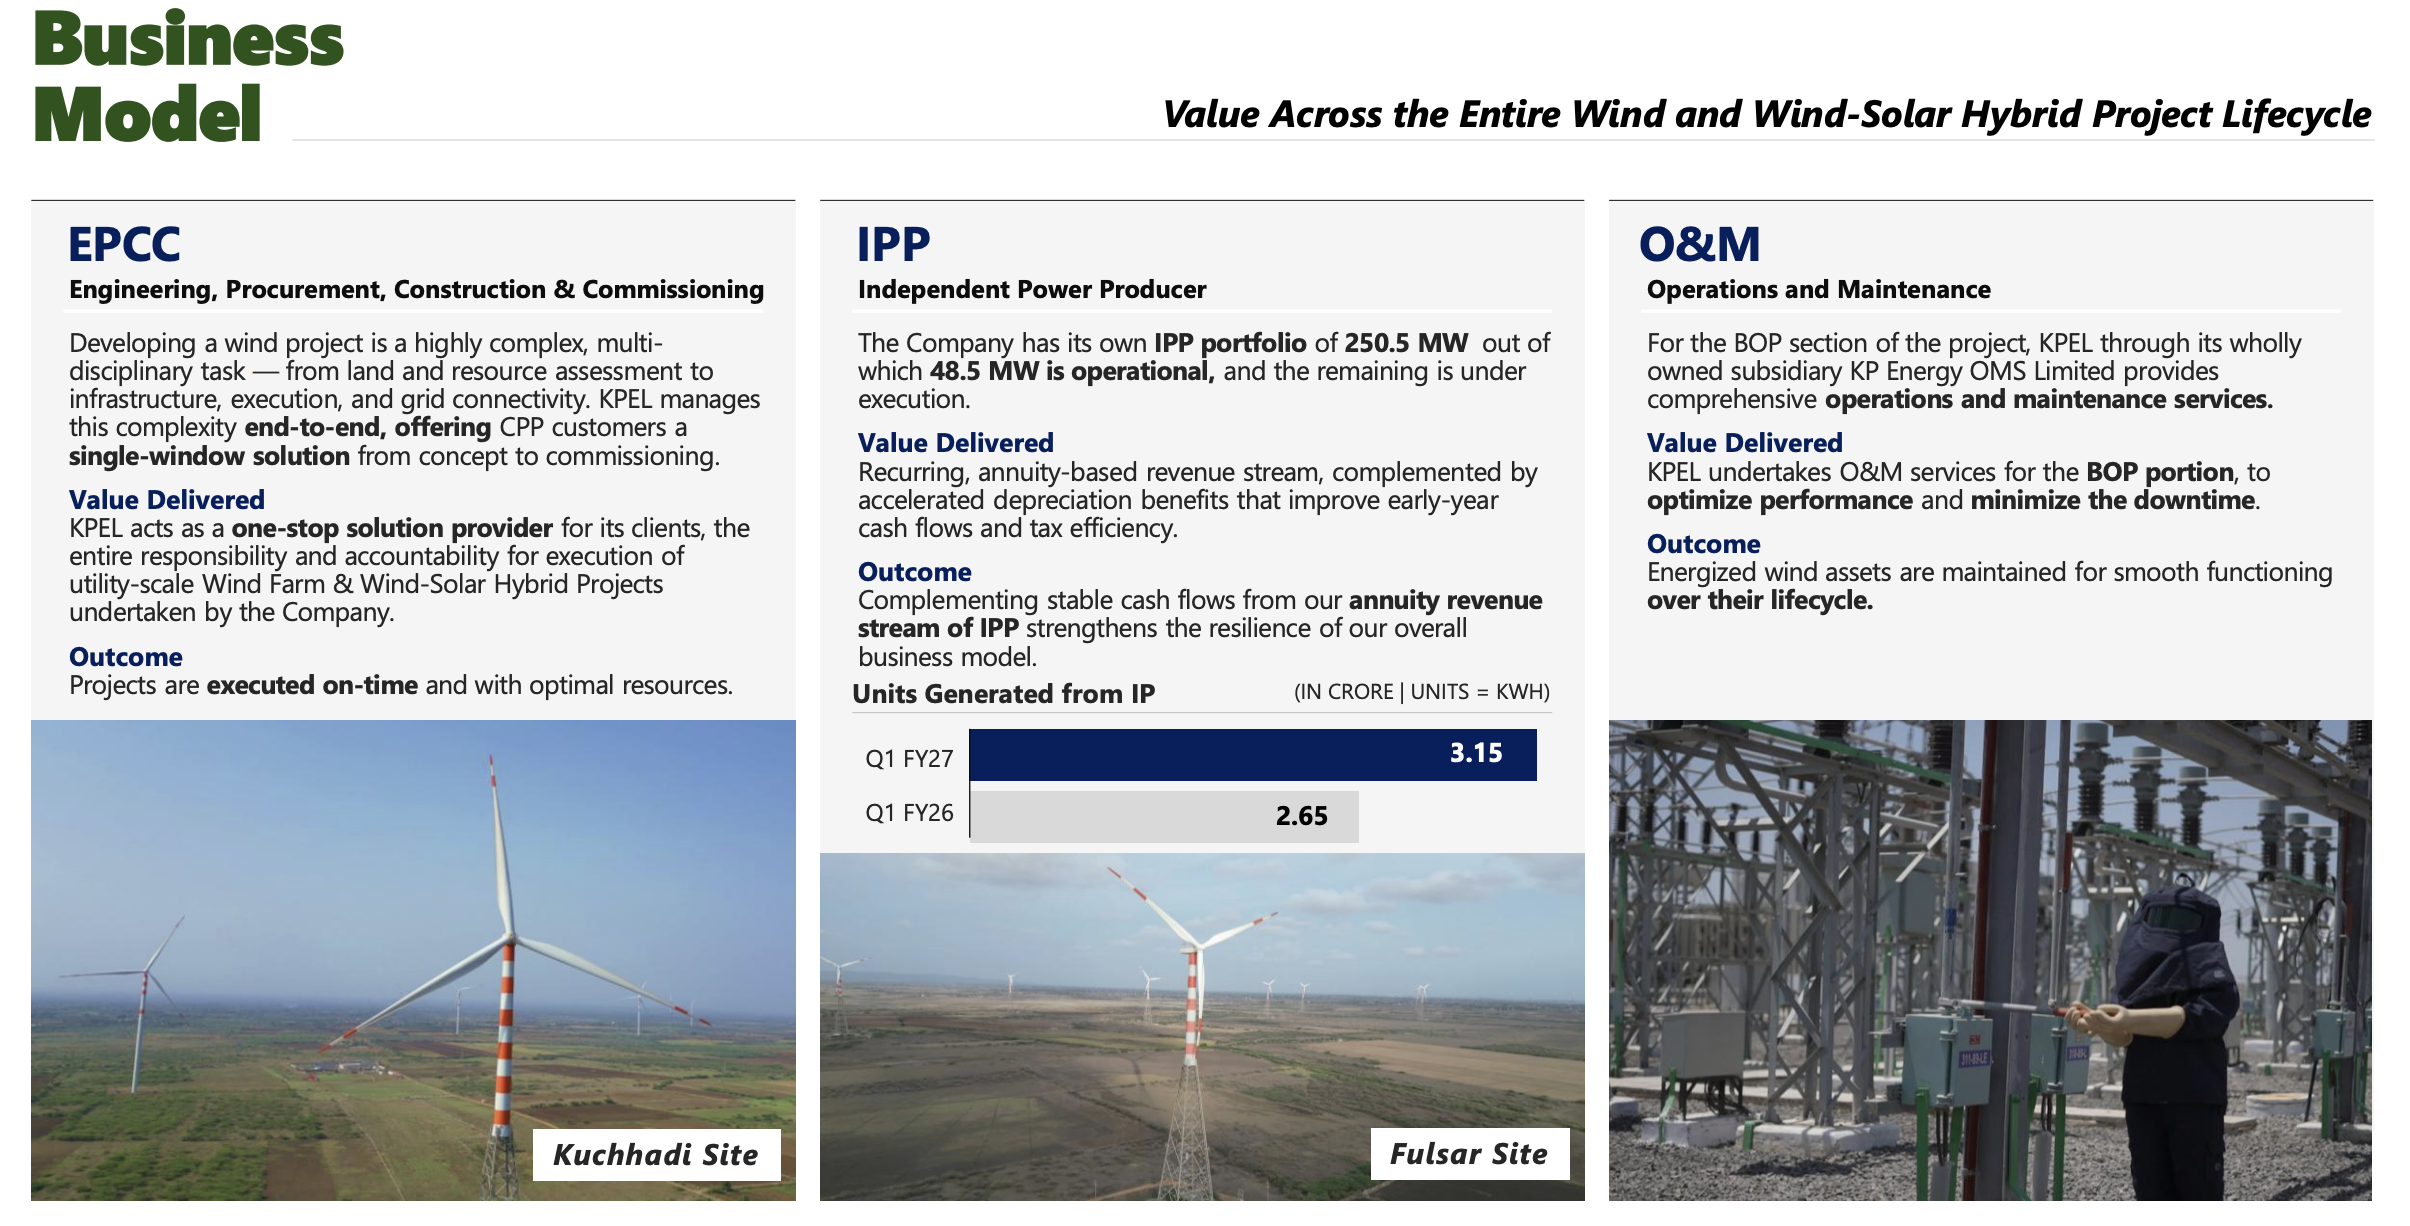
Everybody photographs the turbine. Nobody photographs the 66 kV pooling substation, the access road cut through terrain that objected, or the soil bearing capacity test. K.P. Energy does all the things nobody photographs, then hands over something that spins.
The formal description is balance of plant, which means everything on a wind farm except the turbines themselves. It sounds like an accounting entry and is in fact a construction site the size of a village.
The lifecycle starts with measuring the wind, using met masts and LiDAR, a laser instrument that reads wind speed at height. Then come site identification, land aggregation and right-of-way clearance, which is permission to cross land somebody else owns. Civil foundations, erection and commissioning follow. Power is evacuated through pooling substations and extra-high-voltage lines. Permits are handled with both the state and central transmission networks. Maintenance then runs for the operational life of the asset. One roof, every headache.
Three segments carry the revenue. Infrastructure development, the construction engine, brought ₹504.75 crore of the quarter’s ₹519.46 crore. Sale of power, the producer business, brought ₹11.78 crore against ₹10.14 crore. Operations and maintenance brought ₹2.94 crore against ₹1.16 crore, a rise of 153 per cent from a small base. That portfolio covers 646 MW and runs through a wholly owned subsidiary, KP Energy OMS Limited.
Operational capacity as an independent power producer, which sells electricity to the grid, is 48.5 MW. That splits into 37 MW of wind and 11.5 MW of solar. A further 202