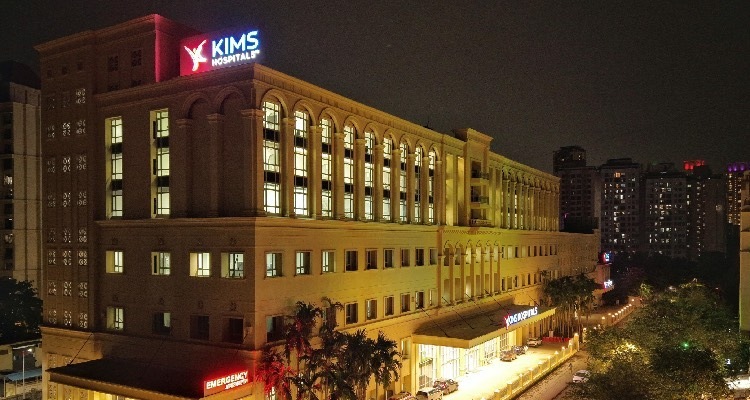
KIMS Ltd March 2026: The ₹4,253 Crore Debt Explosion
Spotted a factual error — a wrong number, date, or fact? Tell us and we will check the source.
Section 1 — At a Glance
Krishna Institute of Medical Sciences Ltd (KIMS) has turned in a highly controversial performance for the fiscal year ended March 31, 2026, delivering an explosive top-line revenue expansion alongside a severe contraction in bottom-line profitability. Consolidated revenue from operations surged 28.6% year-on-year to reach ₹3,904.60 crore. However, consolidated net profit plunged 37.22% to ₹241.40 crore, down from ₹384.50 crore in the previous fiscal year. This dramatic divergence underlines a critical fundamental reality: top-line scale is structurally meaningless if it is rapidly consumed by the operational inefficiencies and severe execution friction of aggressive geographic scaling.
Consolidated Revenue Trajectory
Fiscal Year
Operating Revenue (₹ Crore)
FY24
₹2,498.14
FY25
₹3,035.10
FY26
₹3,904.60
Investor enthusiasm is currently anchored to KIMS’ successful healthcare blueprint across its core markets and a massive footprint expansion that drove group bed capacity to 6,464 beds. However, deep structural concerns have emerged. Total borrowings on the balance sheet ballooned by 66.3% to an astronomical ₹4,252.90 crore, driven by aggressive debt-funded greenfield and inorganic expansions in Maharashtra, Karnataka, and Kerala clusters. Operating margins (OPM) deteriorated sharply from 26% to 21% as new units incurred heavy early-stage operational drag. Furthermore, the sudden rise in promoter share pledges to 10.3% to back family member liabilities has raised urgent corporate governance flags. Can KIMS stabilize its heavily leveraged national healthcare map, or has it built a house of cards?
Section 2 — Introduction
Krishna Institute of Medical Sciences Ltd, long the dominant regional giant of the corporate healthcare sector across Telangana and Andhra Pradesh, finds itself at a historical crossroads. Founded by legendary cardiothoracic surgeon Dr. Bhaskara Rao Bollineni, the group built its unassailable reputation on an incredibly rare combination: low-cost, high-volume tertiary and quaternary healthcare delivered at affordable price points.
This article exists because the regional champion has officially embarked on an aggressive, highly leveraged national expansion roadmap. By moving rapidly into competitive micro-markets across Maharashtra (Nagpur, Nashik, Thane), Karnataka (Bengaluru), and Kerala, KIMS is attempting to replicate its high-acuity medical model outside its home turf. With its stock trading at historically elevated multiples, this structural shift from a concentrated cash-cow cluster to a heavily leveraged, distributed asset network represents a high-stakes corporate gamble that demands deep financial scrutiny.
KIMS operates an integrated multi-disciplinary healthcare engine focused on super-specialties across more than 40 fields, extracting 17% of its revenue from Cardiac Sciences, 13% from Orthopedics, and 11% from Neuro Sciences. It fills its beds through a balanced payor mix where cash collections represent 53%, insurance accounts for 30%, and government-sponsored Aarogyasri schemes stand at a minor 5%.
Specialty Revenue Mix (FY26)
Specialty
Mix %
Cardiac Sciences
17%
Orthopedics
13%
Neuro Sciences
11%
Mother & Child
10%
Gastric Sciences
10%
Renal Sciences
9%
Oncology
6%
Organ Transplant
3%
Others
21%
The KIMS model makes leading local doctors part-owners. Each holds shares in the regional hospital subsidiary where they work. The design is meant to keep doctors from leaving and to hold down fixed salary costs. It also brings patients in from the start. After that, the business is about filling beds. KIMS builds or leases large hospitals and adds doctor-partners. It then works towards breakeven, the point where income covers running costs. Outside its home region, KIMS meets established metro hospital groups.
Section 4 — Financials Overview
Figures are consolidated, in ₹ crore.
Quarterly Trend Analysis
The final quarter of the fiscal year ended March 31, 2026, showcases a clear symptom of structural margin dilution under the weight of newly commissioned assets.
Metric
Mar 2026 (Q4)
YoY (%)
QoQ (%)
Revenue
₹1,074.60
+69.55%
+7.71%
EBITDA / Operating Profit
₹206.50
+29.96%
+3.82%
PAT
₹42.50
-35.11%
-20.41%
EPS (₹)
₹1.06
-35.37%
-20.30%
While top-line quarterly revenue expanded robustly by 69.55% year-on-year to ₹1,074.60